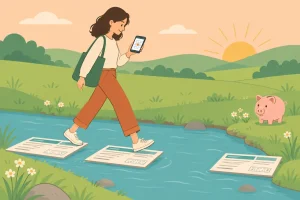
Every month you cross the same stream, one stepping stone per bill and one per paycheck. Most weeks the stones sit just above the water. But every so often a bill drafts on the 28th, your paycheck lands on the 1st, and for three days one stone is missing. You don't fall in because you spent too much — you fall in because the next stone hadn't arrived yet. That splash has a price, and it's called an overdraft fee.
That price is climbing again. According to Reuters' calculations, confirmed by KBRA Financial Intelligence, US banks collected US$1.6 billion in overdraft fees in the third quarter of 2026 — up 9.4% from the prior quarter and the highest quarterly total in four years. JPMorgan Chase and Wells Fargo together charged US$590 million of it, "roughly equal to the rest of the 20 largest banks combined", and overdraft fees were up 23% from the first full quarter of the current administration's second term.
Here's what I find hopeful in all this: a lot of overdrafts aren't really about spending. They're about timing — a bill or autopay that drafts a few days before payday, in a gap that would have closed by itself. And timing, unlike prices or paychecks, is something you can usually rearrange.
#Overdraft Fees Are Back at a Four-Year High
Those numbers come from Stephen Gandel and Douglas Gillison's reporting (Reuters, November 13, 2026), and the story is fair to the banks too: a JPMorgan spokesperson said 75% of transactions in which customers overdraw their accounts carry no fee.
Still, the fees that do land add up to a lot of small splashes, and not everyone reads them as harmless. Mark Zandi, chief economist at Moody's Analytics, named the bigger worry in the same piece: "I wonder if increasing overdrafts may be a leading indicator of developing credit problems." Whether or not he's right, an overdraft is rarely the problem itself — it's a symptom of money and bills arriving out of step.
#The US$5 Limit That Never Took Effect
You may remember headlines about overdrafts getting much cheaper. A CFPB rule would have limited big banks' overdraft fees to as little as US$5, and it was due to take effect on October 1, 2025. It never did. When the CFPB announced the rule, it noted that consumers paid more than US$5.8 billion in reported overdraft and NSF fees in 2023 (CFPB, December 12, 2024); Congress then disapproved the rule through Public Law 119-10, approved on May 9, 2025. Whatever your view of that decision, the practical upshot is simple — no new limit is on its way, so the most reliable protection is the one you control.
#Why So Many Overdrafts Are a Timing Problem
This pattern is long-standing. In a 2014 CFPB analysis, then-Director Richard Cordray said the majority of consumers put money back into their accounts within three days of their overdraft transactions. The typical overdraft fee was US$34, and debit overdrafts were often for less than US$24 (CFPB, 2014). Read together, the shape is hard to miss: a small purchase, a gap of a few days, and a fee bigger than the thing that caused it.
It's the same trap as a merchant late fee, just one step removed — and like any missed payment, the costs tend to stack. An overdraft is a late-fee snowball that starts inside your own bank account.
And right now there's less slack to absorb it. Total US household debt rose US$334 billion (1.8%) in Q3 2026 to US$19.1 trillion, credit card balances rose US$22 billion to US$1.29 trillion, and 5.0% of outstanding debt is in some stage of delinquency — though the Fed's own headline notes delinquency transition rates remain flat (New York Fed, November 10, 2026). Its researchers also found the gap in credit card delinquency between higher- and lower-income neighborhoods has expanded (Liberty Street Economics). Budgets are stretched, not snapping — but when a month has little give, a few days of mistiming matters more.
#How to Fix Your Bill Timing
#1. Line up every due date and autopay against payday
List every bill with its amount and the day it actually leaves your account — rent, utilities, insurance, phone, card minimums, and every subscription or autopay that drafts on its own. Then put your paydays beside them. If you're paid every two weeks and most bills are monthly, they'll drift in and out of step, and you'll spot the stretch where three drafts land in the four days before a paycheck. Autopay is a great money habit, but only when its date suits your cash flow. Subscriptions are the easiest to lose track of, so write down the real renewal date of each one.
Autopays are the stones people lose track of, and that's where BillOut earns its keep. As a bill tracker, it lets you switch on Auto-Pay for any bill that drafts by itself: BillOut marks it as paid on its due date, so it stays on your calendar instead of vanishing into the background. It never pays anything or touches your bank — it just keeps every draft in view, right next to your paycheck.
#2. Ask billers to move due dates
Once you can see the crunch, ask the billers behind it whether they'll move your due date. Some will, some won't, and some let you change it yourself in your online account. Start with the biggest bills that land just before payday, since they're the likeliest to tip you over. Every draft you shift to just after your paycheck is one less stone missing from the stream.
#3. Get a payment reminder early enough to move money
A reminder on the day a bill drafts only tells you what's already happening. A reminder a few days earlier gives you time to move money from savings, hold off on a purchase or call the biller. In BillOut, each bill's payment reminder can go off on the due date itself, one to three days ahead, or up to three weeks out. BillOut can't see your balance, so treat that reminder as your cue to check it — if the account looks thin, you still have time to top it up.
#4. Keep a small buffer
Even with perfect timing, dates wobble: a paycheck lands a day late, an annual renewal you forgot about drafts early. A small cushion left in checking turns those surprises into non-events.
"People underestimate the need for room for error in almost everything they do that involves money."
Morgan Housel, "The Psychology of Money", Collaborative Fund (June 1, 2018)
A buffer is that room for error, sitting quietly in your account. It doesn't have to be big to start — it works like building a small cushion for a price hike before it lands.
Download BillOut — Bill Reminder App
See every bill coming before it drafts
#Close the Gap Before It Costs You
You can't set your bank's fee policy, and you can't make payday come sooner. But you can decide when your bills land, how early you hear about them, and how much room you leave yourself. Most months, that's enough to keep every stepping stone in place.
Start with your next payday: map every draft around it and move whatever falls in the gap. Paying a fee for three days of bad timing is one of the most avoidable costs there is — and fixing it is a money habit that keeps paying you back.
Important Notice
The opinions expressed in this article are for general informational purposes only and are not intended to provide specific advice or recommendations for any individual or on any specific security or investment product and should not be relied on in place of professional advice. It is only intended to provide education about the financial industry.
BillOut is not responsible for the content of any site owned by a third party that may be linked to this article and no warranty is made by us concerning the suitability, accuracy or timeliness of the content of any site that may be linked to this article. BillOut disclaims all liability (except for any liability which by law cannot be excluded) for any error, inaccuracy, or omission from the information contained in this article and any loss or damage suffered by any person directly or indirectly through relying on this information.